Managing household finances has become increasingly challenging as the cost of everyday essentials continues to affect family budgets. From groceries and transportation to rent, electricity, healthcare, and education, many people are finding that their regular income does not stretch as far as it once did. Even individuals who maintain steady employment may struggle to balance monthly expenses with savings goals, debt repayments, and unexpected financial responsibilities. In this environment, budgeting is no longer simply a method of tracking spending. It is an important financial habit that helps people make informed decisions, prepare for uncertainty, and maintain greater control over their money.
Smart budgeting begins with understanding how income is used and identifying opportunities to make spending more efficient. Rather than eliminating every enjoyable purchase or adopting an unrealistic savings target, individuals can create a practical plan that reflects their actual needs and circumstances. The objective is to prioritize essential expenses, reduce avoidable costs, and reserve money for future requirements. Resources and financial discussions associated with wealthtale.com can serve as a starting point for exploring budgeting ideas, but the most effective approach is one that individuals adapt to their own income, responsibilities, and financial priorities.
As living costs fluctuate, a flexible budget becomes especially valuable. Prices may change from month to month, household requirements can increase, and unexpected expenses can disrupt even a carefully prepared financial plan. A successful budgeting strategy therefore combines regular expense tracking, realistic spending limits, emergency preparation, and consistent reviews. By applying these principles, individuals can build a stronger financial foundation without depending on drastic lifestyle changes.
Understanding Why Rising Living Costs Affect Household Budgets
Inflation and changing market conditions influence how much people pay for essential goods and services. When grocery prices rise, fuel becomes more expensive, or housing costs increase, households often need to spend a larger share of their income simply to maintain their existing standard of living. The impact is particularly noticeable for people whose salaries remain relatively stable while everyday expenses increase. A family that previously had enough money for monthly bills and savings may discover that the same income now leaves little room for unexpected purchases or long-term financial goals.
The challenge is not always caused by a single expensive category. Often, several smaller increases combine to create substantial financial pressure. A higher electricity bill, a slightly more expensive grocery shop, additional transportation costs, and rising subscription fees may appear manageable individually. Together, however, they can reduce the amount available for savings and other priorities. Understanding these changes requires examining spending patterns rather than relying on assumptions about where the money goes. Reviewing bank statements, payment records, and household bills helps reveal which expenses have increased and which purchases can be adjusted without affecting essential needs.
Another important consideration is the difference between necessary spending and spending driven by convenience or habit. Essential expenses include housing, food, utilities, transportation, healthcare, and other obligations that support everyday life. Discretionary expenses may include frequent restaurant meals, entertainment subscriptions, impulse purchases, and nonessential upgrades. The distinction is not always absolute because individual circumstances vary, but separating these categories makes it easier to identify realistic savings opportunities. A thoughtful budget protects important needs while allowing reasonable flexibility for enjoyment.
Building a Realistic Monthly Budget That Works
A useful monthly budget should reflect actual financial conditions rather than an ideal situation that is difficult to maintain. The first step is calculating total take-home income after taxes and other mandatory deductions. People with regular salaries can usually estimate this amount from their payslips, while freelancers, business owners, and workers with variable earnings may need to calculate an average based on several months of income. Using a conservative estimate is particularly helpful when earnings fluctuate because it reduces the risk of committing money that may not arrive as expected.
After determining income, list fixed expenses, variable necessities, debt payments, savings contributions, and discretionary purchases. Fixed expenses include costs such as rent, insurance premiums, and scheduled loan repayments. Variable necessities include groceries, fuel, household supplies, and utility bills. Savings should appear as a planned budget category instead of receiving whatever money remains at the end of the month. This approach encourages consistent progress and makes it easier to identify whether spending commitments exceed available resources.
The budgeting methods discussed through wealthtale.com can be considered alongside established approaches such as zero-based budgeting and percentage-based budgeting. A zero-based budget assigns a purpose to every unit of income, including spending, savings, and debt repayment. Percentage-based methods divide income among broad categories, offering a simpler framework for people who prefer fewer calculations. Neither approach is automatically suitable for everyone. Someone managing irregular income or substantial medical expenses may need a more flexible system than a household with predictable earnings and relatively stable bills.
The following table illustrates how a hypothetical household might organize a monthly income of ₹50,000. These figures are examples rather than recommended amounts, and the appropriate distribution will depend on local prices, family size, debt obligations, and personal circumstances.
| Budget category | Monthly allocation | Percentage |
|---|---|---|
| Housing and utilities | ₹15,000 | 30% |
| Groceries and household needs | ₹8,000 | 16% |
| Transportation | ₹4,000 | 8% |
| Healthcare and insurance | ₹3,000 | 6% |
| Debt repayments | ₹5,000 | 10% |
| Savings and emergency fund | ₹7,000 | 14% |
| Personal spending and entertainment | ₹3,000 | 6% |
| Education and miscellaneous expenses | ₹5,000 | 10% |
| Total | ₹50,000 | 100% |
This example shows why budgeting should be treated as a connected financial plan rather than a collection of isolated spending limits. If rent increases or medical expenses become unavoidable, the household may need to adjust discretionary spending or revise other flexible categories. If debt repayments become smaller, some of the released money could be redirected toward savings. The aim is to maintain balance while ensuring that essential obligations and financial priorities receive appropriate attention.
Practical Ways to Reduce Everyday Expenses
Reducing everyday costs does not necessarily require a dramatic change in lifestyle. In many households, the most effective improvements come from identifying repeated expenses that offer limited value. Grocery shopping provides a useful example. Planning meals in advance, preparing a shopping list, comparing unit prices, and using ingredients before they expire can help reduce waste. Buying larger quantities may offer savings for frequently used products, but only when the items can be stored safely and used before their quality deteriorates. Discounts are beneficial only when they reduce the cost of something the household genuinely needs.
Transportation and utility bills also deserve regular attention. Combining errands into one trip, using public transportation when practical, sharing rides, and maintaining vehicles properly may reduce travel costs. At home, switching off unused appliances, improving lighting efficiency, limiting unnecessary heating or cooling, and checking for water leaks can help control utility consumption. The actual savings will depend on household habits and local tariffs, so reviewing bills over several months is more informative than assuming that a particular measure will always produce the same result.
Recurring digital payments are another frequently overlooked source of unnecessary expenditure. Entertainment platforms, software subscriptions, premium memberships, and automatic renewals can continue charging even when people rarely use the services. Reviewing these payments every month helps identify subscriptions that can be cancelled, downgraded, or replaced with less expensive alternatives. However, it is important to consider the practical value of a service before removing it. A subscription that supports education, professional development, or regular work may be more valuable than its price initially suggests.
A few consistent habits can make expense reduction easier to maintain:
-
Prepare a weekly spending plan for groceries, transportation, and personal purchases.
-
Compare prices and check the total cost before making significant purchases.
-
Review recurring subscriptions and cancel services that no longer provide sufficient value.
-
Set a reasonable limit for discretionary spending and track it throughout the month.
-
Wait before making nonessential purchases to reduce impulse buying.
These actions work best when they are repeated consistently rather than applied for only a few days. Small savings may appear insignificant at first, but the combined effect can become meaningful over several months. The money saved should ideally be assigned a purpose, such as building an emergency fund, paying down expensive debt, or covering an upcoming household expense.
Using wealthtale.com to Explore Better Financial Habits
Financial education can help individuals understand budgeting concepts and compare different approaches to managing money. wealthtale.com can be treated as a starting point for exploring financial topics and considering practical ways to organize spending. Readers should evaluate any financial information they encounter carefully, especially when it involves investment returns, borrowing decisions, financial products, or promises of unusually high savings. General budgeting guidance can provide useful ideas, but individual decisions should always reflect personal circumstances and verified information.
The most useful financial resource is one that encourages informed decision-making instead of promoting a single solution for every household. For example, a person with limited savings may benefit from learning how to establish an emergency reserve before pursuing more ambitious financial goals. Someone carrying expensive credit card debt may need to prioritize repayment while maintaining enough cash to handle urgent expenses. A household with stable finances may instead focus on saving for education, a home purchase, retirement, or other long-term objectives. Each situation calls for a different combination of priorities.
Readers should also distinguish between educational content and personalized financial advice. Articles can explain budgeting frameworks, describe common financial risks, and introduce methods for tracking expenses. They cannot automatically account for every detail of an individual’s income, legal obligations, tax position, or financial commitments. Before acting on a significant recommendation, it is sensible to check the underlying information, understand the risks, and consult a qualified professional when the decision is complex.
Ultimately, the value of wealthtale.com or any comparable educational resource depends on how effectively the information supports real financial decisions. Reading about budgeting is a useful first step, but meaningful improvement comes from applying suitable ideas, measuring their results, and adjusting the approach when circumstances change.
Creating an Emergency Fund for Financial Security
An emergency fund protects a household against unexpected expenses that would otherwise disrupt its budget. Common examples include medical bills, urgent home repairs, essential vehicle maintenance, temporary unemployment, and sudden family responsibilities. Without accessible savings, people may have to rely on high-interest borrowing, delay necessary payments, or sell assets at an inconvenient time. An emergency reserve provides a financial buffer that makes these situations easier to manage.
The amount required depends on household circumstances. Someone with stable employment, low fixed expenses, and few dependents may have different needs from a freelancer supporting a family with several ongoing financial commitments. A practical approach is to begin with a small, achievable target that could cover an urgent expense. Once that initial reserve is established, savings can gradually grow toward an amount covering several months of essential living costs. Building a substantial reserve may take time, so progress should be measured against the household’s actual resources rather than an unrealistic deadline.
Consistency matters more than the size of an initial contribution. Setting aside a manageable amount after each payday can establish a dependable savings habit. People with irregular earnings may contribute a percentage of income whenever they receive payment, provided essential bills and minimum debt obligations remain covered. Additional money from bonuses, refunds, or temporary reductions in spending can also support the fund. Emergency savings should generally remain accessible in a suitable low-risk account rather than being placed entirely in volatile investments.
It is equally important to define what qualifies as an emergency. Planned holidays, routine shopping, and predictable annual bills should normally have separate savings categories. This distinction prevents the emergency fund from becoming a general spending account and preserves its purpose when a genuine financial problem arises.
Managing Debt Without Sacrificing Essential Needs
Debt management is an important part of budgeting when living costs increase. Loan instalments and credit card payments reduce the income available for food, housing, savings, and other necessities. If borrowing becomes expensive, interest charges may create additional pressure and make it harder to regain financial stability. A clear overview of outstanding balances, interest rates, minimum payments, and repayment dates helps individuals understand which obligations require the greatest attention.

Two common repayment approaches are the debt avalanche and the debt snowball methods. The avalanche method directs extra payments toward the debt with the highest interest rate while minimum payments continue on other accounts. This approach can reduce total interest costs when followed consistently. The snowball method focuses extra payments on the smallest balance first, potentially providing a sense of progress that helps people remain motivated. The most suitable strategy depends on interest rates, account conditions, repayment capacity, and individual preferences.
Before making additional repayments, households should ensure that essential expenses and required minimum payments are covered. Using every available rupee to reduce debt can leave a person vulnerable to an unexpected bill, potentially forcing them to borrow again. A modest emergency reserve can provide a useful balance between debt reduction and financial resilience. People struggling to meet minimum payments should contact their lenders promptly to discuss available options rather than ignoring notices or assuming the situation will resolve itself.
Borrowing should also be evaluated carefully before new commitments are accepted. A monthly instalment may appear affordable in isolation, but the total repayment amount, fees, interest rate, and length of the agreement determine the actual cost. A purchase that fits within a monthly budget may still create unnecessary long-term pressure if it limits the ability to save or respond to unexpected expenses.
Adapting Your Budget to Changing Prices and Income
A budget should not remain unchanged when the financial environment shifts. Grocery prices, housing costs, transportation expenses, and household bills may rise at different rates, while income can change because of salary adjustments, freelance work, job transitions, or family circumstances. Reviewing the budget regularly allows individuals to identify these changes before they create serious problems. A monthly review is often sufficient for predictable household finances, while people with irregular income or rapidly changing expenses may benefit from checking their spending more frequently.
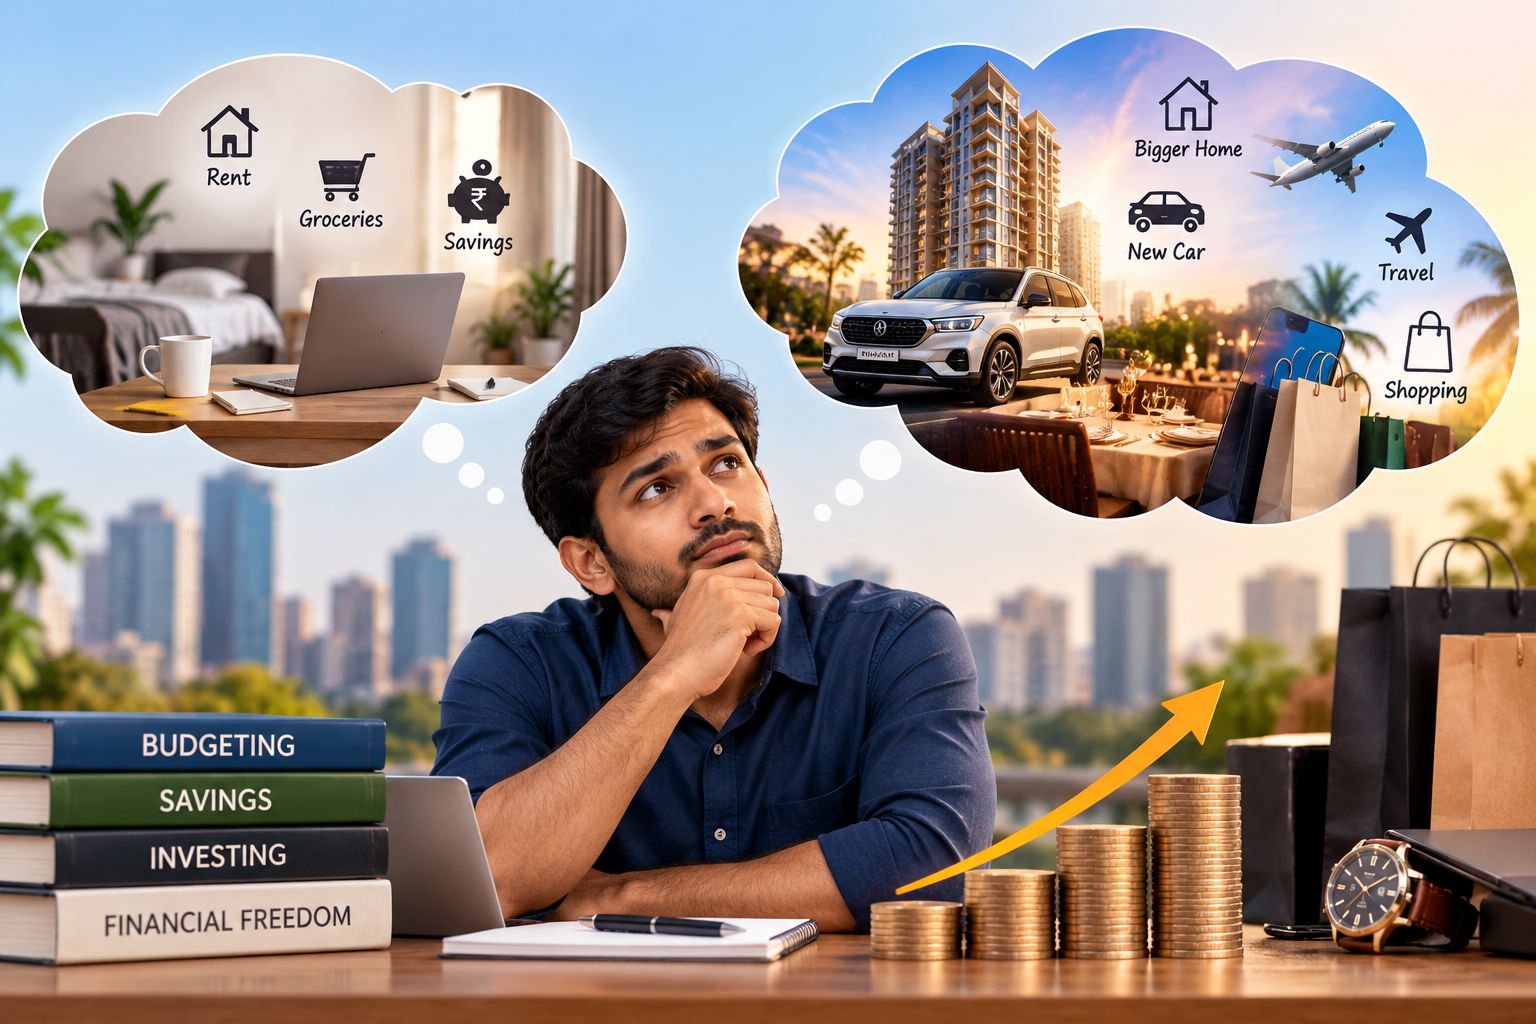
Start by comparing actual spending with the amounts planned at the beginning of the month. If groceries repeatedly exceed the budget, examine whether prices have increased, food waste has grown, or the original estimate was unrealistic. If transportation costs are higher than expected, consider whether the difference comes from fuel prices, additional travel, maintenance, or changing commuting requirements. Understanding the cause makes it easier to choose an effective response instead of simply imposing a lower spending limit that cannot be maintained.
It is also helpful to plan for predictable irregular expenses. Annual insurance premiums, school fees, vehicle servicing, festive occasions, and home maintenance may not occur every month, but they should still be included in the financial plan. Estimating the annual cost and setting aside a monthly portion can reduce the pressure when payment becomes due. For example, an expense of ₹12,000 expected once a year could be funded by saving ₹1,000 per month, provided the timing and available cash flow allow it.
When income increases, avoid automatically allowing every additional rupee to become a new expense. A salary increase may create an opportunity to strengthen savings, accelerate debt repayment, or fund an important goal. At the same time, when income falls, prioritize housing, essential food, healthcare, utilities, and necessary transportation. Temporary reductions in discretionary spending may help protect these obligations while a longer-term adjustment is developed.
Using Simple Digital Tools to Track Spending
Digital budgeting tools can make expense tracking more convenient by organizing transactions, displaying spending patterns, and helping users monitor progress toward financial goals. Spreadsheet applications and budgeting software can categorize expenses and calculate totals automatically, reducing the time needed for manual calculations. Some banking applications also provide transaction summaries that help users understand where their money is going. The right option is the one that fits an individual’s habits and is simple enough to use consistently.
A basic spreadsheet can be effective for people who prefer to maintain direct control over their records. It can include the date, expense category, amount, payment method, and whether the transaction was planned or unexpected. At the end of the month, totals can be compared with the budget to identify categories that need adjustment. More advanced tools may offer alerts and visual reports, but additional features are not essential if a simple system already provides the information needed to make decisions.
Privacy and security should remain important considerations when using financial technology. Individuals should review the permissions requested by applications, protect accounts with strong authentication, and avoid sharing banking passwords or sensitive account information with unverified services. Any tool that claims to provide financial insights should be assessed carefully before personal information is supplied. Convenience is useful, but it should not come at the expense of financial security.
Technology is most effective when it supports regular habits instead of replacing them. A notification cannot solve overspending unless the user takes appropriate action, and an expense report is only useful when its findings influence future decisions. Combining digital records with a short weekly review creates a practical system for keeping spending visible and maintaining control over financial choices.
Conclusion
Rising living costs make effective budgeting an essential part of maintaining financial stability. Although individuals cannot control every price increase or economic change, they can improve how they organize income, prioritize expenses, manage debt, and prepare for unexpected financial challenges. A realistic budget creates a clearer picture of household finances and helps people identify practical ways to reduce unnecessary spending without sacrificing important needs. The most effective strategies begin with understanding actual expenses, setting achievable savings targets, and reviewing spending patterns regularly. Meal planning, subscription reviews, energy conservation, debt repayment planning, and emergency savings can all contribute to stronger financial habits when applied consistently. Digital tools and financial education can provide additional support, but successful budgeting ultimately depends on making informed decisions and adjusting the plan as circumstances change.